Your adjuster just used the word “total loss,” and the number they’re offering feels low - lower than what you thought your car was worth, and nowhere near what it would cost to buy something similar today. That gap between expectation and offer is one of the most common friction points in the whole claims process, and understanding how the number was actually calculated is the first step to pushing back on it, if it deserves pushing back on.
What “Write-Off” Actually Means
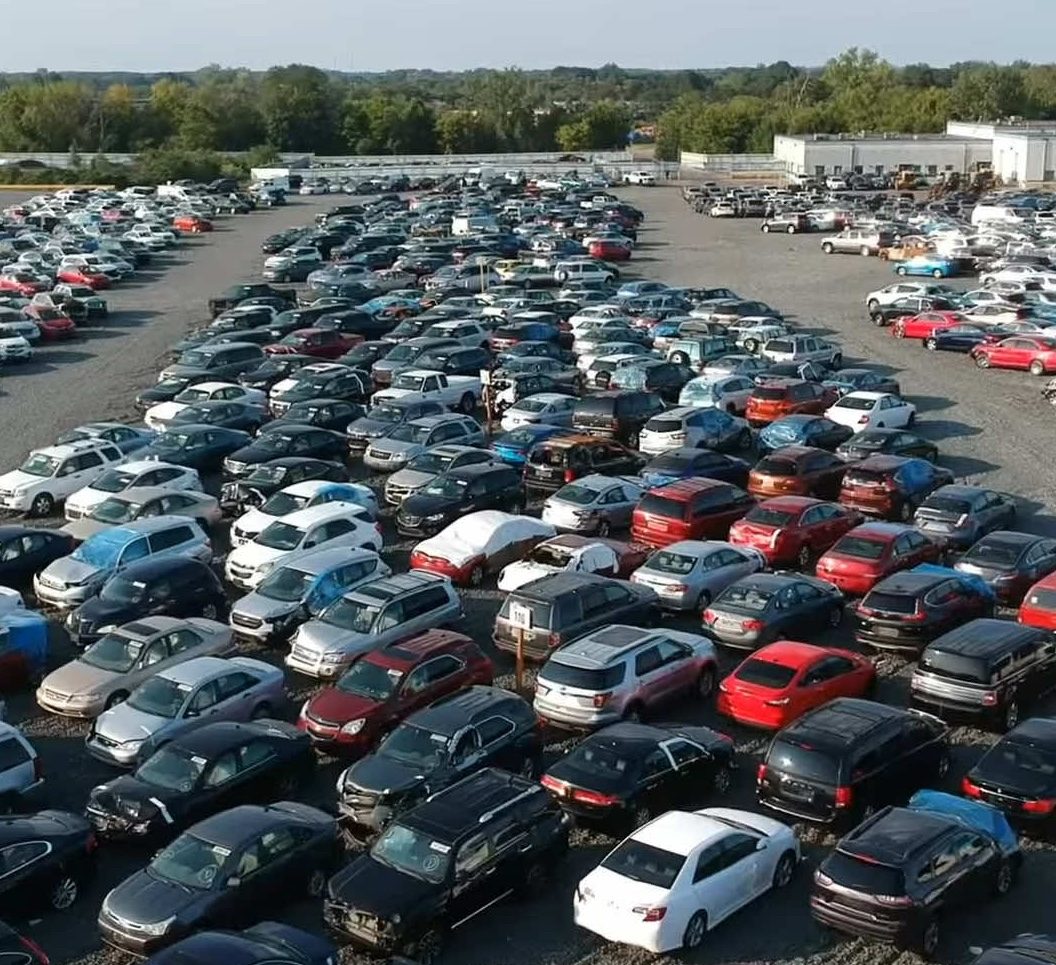
A vehicle is declared a total loss (a “write-off”) when the cost to repair it exceeds what the insurer considers it worth - sometimes because the repair itself would cost more than the car’s value, and sometimes because of state or insurer thresholds tied to that comparison. Once that determination is made, your insurer doesn’t pay for repairs; instead, they pay you the vehicle’s value immediately before the crash, and typically take possession of the salvage vehicle in exchange (unless you arrange a buyback - more on that below).
Actual Cash Value, Explained
The number your insurer pays is called Actual Cash Value (ACV). This is a specific and often misunderstood concept: ACV is what your vehicle was worth in the market right before the accident - not what it would cost to replace it with something new or equivalent, and not what you paid for it originally.
This trips people up constantly. If you bought your car three years ago and it’s depreciated since, your ACV reflects that depreciation, even though replacing it today - with used vehicle prices what they are - might cost meaningfully more than the payout. ACV is a backward-looking market valuation of your specific vehicle in its specific pre-crash condition, not a forward-looking replacement budget.
How Insurers Calculate ACV
Insurers typically arrive at an ACV figure using a combination of:
- Comparable vehicle listings - similar year, make, model, trim, mileage, and condition, sold or listed recently in a comparable market.
- Vehicle condition before the crash - mileage, wear, any pre-existing damage, maintenance history, and aftermarket modifications can all move the number up or down.
- Regional market factors - vehicle values differ across America, and insurers generally value based on your local or regional market rather than a national average.
- Industry valuation guides and tools many insurers use as a starting point, cross-referenced against comparable listings.
The result is a number the insurer considers defensible and market-based - but “defensible” doesn’t always mean “the highest reasonable number,” which is exactly why negotiation exists as a normal part of this process.
How to Negotiate ACV
You are not required to simply accept the first number your insurer offers. A well-documented pushback is a normal and often effective part of a total-loss claim:
- Find genuinely comparable vehicles. Look for the same year, make, model, and roughly the same trim, mileage, and condition - ideally several listings, not just one - from dealers or private sellers in your region.
- Document your vehicle’s actual pre-crash condition. Recent maintenance records, upgraded tires, a clean interior, low mileage relative to its age - anything that supports a higher valuation than a generic estimate might assume.
- Present the comparables to your adjuster directly, and ask them to explain how their number compares to yours. A reasonable insurer will consider well-documented comparable listings; if yours won’t, that’s worth escalating.
- Get it in writing once you reach an agreed number, along with a clear explanation of what it covers (and whether taxes and licensing fees are included - this varies, so ask directly).
- Escalate if you’re at an impasse. Start with your insurer’s internal review process, and check whether your policy includes an appraisal clause - many policies do, offering a formal, structured way to resolve exactly this kind of valuation dispute without going to court. See how to dispute an insurance settlement in the U.S. for the full escalation path.
Salvage and Buyback: A General Option
In many cases, if you’d rather keep the vehicle than hand it over - maybe it still runs, or you want the parts, or it has sentimental value - you can ask your insurer about a salvage buyback. This generally means the insurer deducts an agreed salvage value from your ACV payout and lets you keep the vehicle, which is then typically branded with a salvage or rebuilt title depending on your state’s rules. Whether this is available, and what the exact terms are, varies by insurer and by state, so treat it as a general option worth asking about rather than something you’re automatically entitled to. If you go this route, understand that a salvage-branded vehicle can affect future insurability and resale value - worth researching your specific state branding rules before committing.
Total Loss and Towing
If your vehicle needed a tow because of the accident that led to the total loss, that cost is generally covered as part of the same claim, along with any storage fees while the total-loss determination and valuation process play out. Keep every invoice - these fees can add up if the valuation process takes a while, and you’ll want them accounted for separately from the ACV payout itself. See who pays for towing after an accident for more detail.
Quick Reference
| Term | What It Means |
|---|---|
| Write-off / total loss | Repair cost exceeds the insurer’s threshold relative to vehicle value |
| Actual Cash Value (ACV) | Market value of your specific vehicle immediately before the crash |
| Comparables | Similar listings used to support a higher (or confirm a lower) ACV |
| Salvage buyback | Option to keep the vehicle for an agreed deduction from your payout, subject to state branding rules |
| Appraisal clause | A formal dispute-resolution process some policies include for valuation disagreements |
FAQ
Does ACV cover what it would cost to replace my car today? No. ACV reflects your vehicle’s market value immediately before the crash, not current replacement cost - a distinction that matters especially if used vehicle prices have risen since you bought it.
Can I negotiate my insurer’s total loss offer? Yes. Bringing genuinely comparable vehicle listings and documentation of your car’s actual pre-crash condition is a normal, often effective way to push back on a low valuation.
What happens to my car after it’s declared a total loss? Typically the insurer takes possession of the salvage vehicle in exchange for the ACV payout, unless you arrange a buyback to keep it, subject to your state’s salvage title rules.
Is a salvage buyback a good idea? It depends on your situation - it can make sense if the vehicle has value to you beyond the payout, but a salvage-branded title can affect future insurability and resale value, so weigh that before deciding.
What if my insurer and I can’t agree on ACV? Escalate through your insurer’s internal review process, and check whether your policy includes an appraisal clause, which many do specifically for valuation disputes like this. See how to dispute an insurance settlement in the U.S..
Total loss processes and ACV calculations vary by insurer and state - this is general guidance, not a valuation of your specific vehicle. Confirm the details of your claim directly with your insurer. For the full claims picture, see the complete guide to car insurance claims in the U.S.. If you need to move a written-off vehicle, find a tow truck near you or check accident recovery towing.